
Myth-busting: common misconceptions about fintech loans and cashback cards
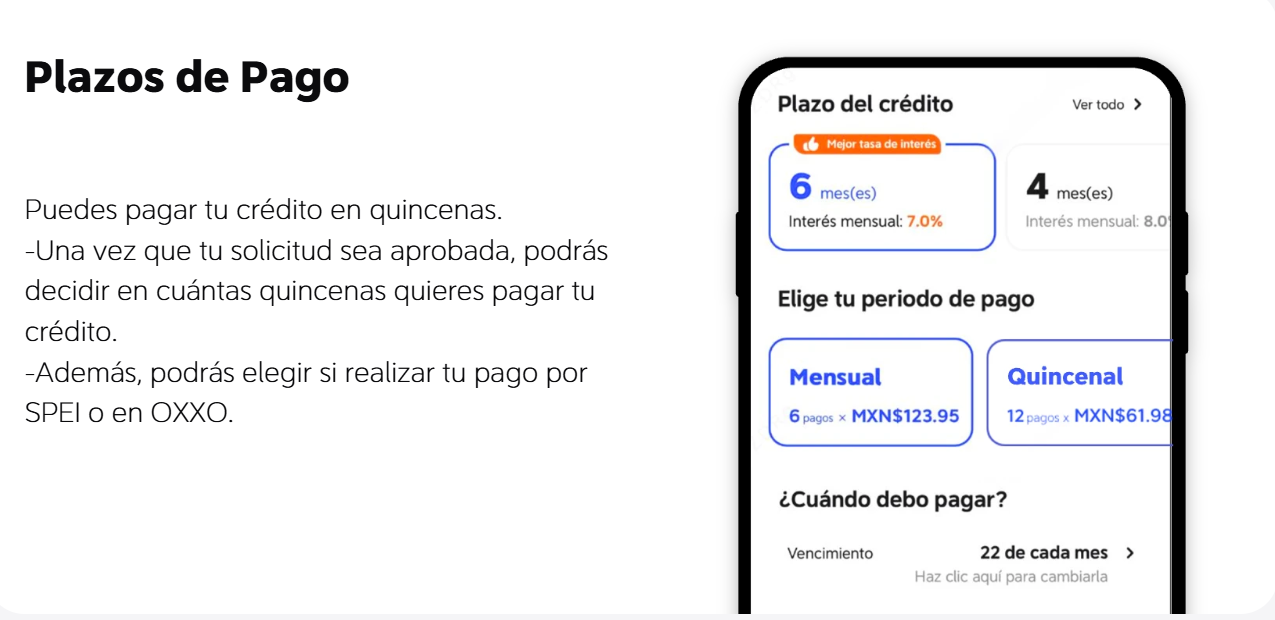
Many people assume that any online loan or cashback credit card pitched through an app must be a scam. That blanket belief hurts consumers more than it helps—there are legitimate services operating under clear regulation, and there are predatory ones hiding behind polished interfaces. Start by separating form from function: a well-known marketplace or ride-hailing brand offering loan products doesn’t automatically mean fraud. At the same time, brand recognition isn’t a substitute for contract review—so check the fine print and the provider’s licensing. For those exploring ride-hailing linked financing, a credible starting point is an official product page such as didi prestamos, but treat it like any other lender: read rates and terms carefully.
How to verify legitimacy before you apply
Regulation matters. Mexico’s Fintech Law of 2018 created a framework that many compliant platforms follow; seeing registration with the Comisión Nacional Bancaria y de Valores (CNBV) or references to that framework is a positive signal. Look for clear disclosures of APR, repayment schedule, and underwriting criteria. Verify secure connections (HTTPS), transparent contact information, and independent reviews. When comparing options, include traditional bank offers and fintech alternatives like online creditos en linea—their underwriting models differ and that affects approval speed and cost. Use concrete checkpoints: the exact APR number, whether the product reports activity to credit bureaus (impacting your credit score), and whether cashback rewards are conditional or unconditional.
Red flags, practical checks, and a short human aside
Watch for these immediate warnings and run quick tests before sharing documents or bank details:
– Demands for upfront fees described as “processing” or “verification” before funds are released. – Vague or shifting APR figures; anything not shown as an annual percentage rate is suspect. – Poor or no contract copy provided before acceptance. – Pressure to accept an offer immediately via chat or call. – Requests to transfer money to a personal account rather than a business bank account.
Authenticate identity steps yourself: call a listed customer-service number from an official website rather than the number in an unsolicited message. Use a secure device and confirm your digital wallet permissions. Sometimes a quick local check in Mexico City forums or a trusted consumer-protection page reveals problems you wouldn’t find on the app store listing—small effort, big payoff.
Comparing DiDi-linked finance products to banks and other fintechs
Comparison points should be practical: net cost (APR minus cashback value), flexibility of repayment, and effect on your credit score. Cashback can lower effective cost, but terms matter—some cards offer 1–2% cashback with caps, which may not offset a high APR if you carry a balance. Banks usually have stricter underwriting and slower approvals but clearer dispute resolution; many fintech lenders offer faster decisions with more flexible acceptance criteria. If quick liquidity is the goal, weigh speed against price. If building credit matters, choose products that report to credit bureaus. Keep a record of statements and approval terms—these are your protection if a dispute arises.
Three golden rules for choosing the right offer
1) Prioritise transparent cost metrics: an offer is useful when APR, fees, and cashback mechanics are clearly stated and easy to calculate. 2) Validate legal standing and customer support: confirm registration references and test support responsiveness before committing. 3) Match product to need: short-term emergency financing should favour speed and low fixed fees; long-term balances favour lower APR and credit-building features.
These metrics make evaluating options straightforward and measurable. For many users seeking mobility-linked financing or cashback benefits, practical value comes from predictable costs and clear recourse—exactly the areas where regulated platforms can help. DiDi Finanzas fits into that landscape as a branded solution that can simplify access to credit while offering transparent reward mechanics—use the rules above to confirm it’s the right fit for you. –