
User-first flavor: why this matters
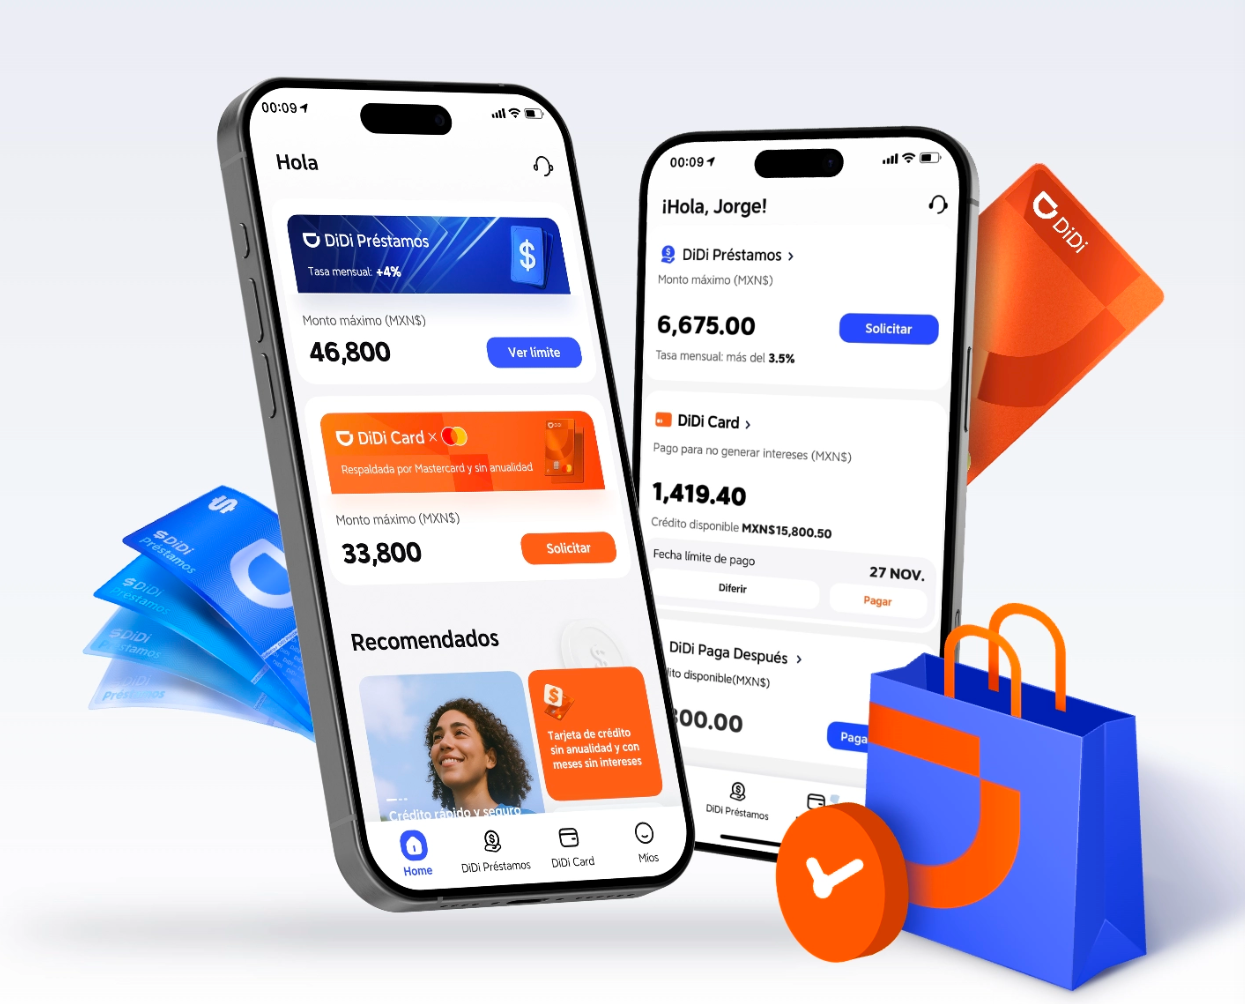
The Didi card serves a compact menu of perks aimed at people who move—commuters, gig drivers, urban shoppers. From the first tap it feels deliberate: cashback that lands frequently, a modest annual fee that doesn’t sting, and a rewards rhythm built around everyday spending. I tested the contours through didi finanzas and found the experience focused on making small wins consistent rather than promising a single, dramatic payoff. The interface, balance updates and statement clarity read like a clean recipe: quick, sensical, and satisfying.
What’s on the menu: core features and mechanics
The card presents a short list of ingredients that matter: cashback on rides and select merchants, a simple rewards program that converts points into credits, contactless payments that feel immediate, and integration with a digital wallet. Industry terms to note: APR is competitive for the segment, credit limit adjusts with usage history, and transaction fees are visible up front. Texture-wise, the rewards pop on small purchases—think of them as seasoning that accumulates tastefully over time.
How it performs in the wild — a commuter’s tasting notes
During a week in Mexico City my routine leaned on the card for short rides and café stops. The didi finanzas app kept a neat tally of cashback and rewards, which landed within a billing cycle and reduced the sting of routine expenses. Balance alerts came through without noise; payments posted smoothly. The most noticeable thing: the card’s benefits crystallize for frequent users—drivers and regular riders see faster payoff. For occasional users the math is gentler, but still pleasant when you stack benefits with the app’s offers.
Common mistakes that spoil the flavor
Users often treat rewards like garnish instead of the main course. Mistake one: carrying a revolving balance while chasing cashback—interest (APR) can erode gains. Mistake two: not linking the card to the digital wallet or missing merchant-category bonuses. Mistake three: ignoring redemption rules—points expire or apply only to certain purchases. Avoid these and the rewards behave like consistent, savory returns rather than vanish into bureaucracy.
Alternatives to sample before you commit
If you want contrast, try a bank-issued cash-back credit card, a fintech wallet with no annual fee, or a transport-specific loyalty card. Bank cards usually offer higher credit limits and broader acceptance; fintechs can be lighter on fees and slicker in-app. The Didi card sits between those: better tailored for mobility and daily micro-spending than for high-limit purchases or travel perks. Choose based on primary spend patterns—commuting and local errands lean toward Didi’s strength, large purchases do not.
Design choices and a few operational notes
The product design favors clarity over complexity. Statements are readable. Rewards categories are explicit. Linking the card to your phone’s wallet is immediate and reduces friction at checkout. One small caveat—promotions shift seasonally, so keep an eye on in-app announcements for limited-time boosts. Also, if you plan to use the card overseas, confirm any foreign transaction fee details before you leave.
Three golden rules to evaluate any mobility-focused card
1) Measure net benefit: calculate expected cashback minus annual fee and likely interest. That number tells you whether the card truly saves money. 2) Match categories to reality: your actual commute, ride-share habits, and recurring local spends should map to the card’s reward categories. 3) Check access and control: smooth integration with a digital wallet and transparent billing reduce user friction. These metrics keep decisions pragmatic and repeatable—no fluff, just measurable outcomes that reflect everyday use.
After tasting features, testing them on real streets and comparing alternatives, the practical value becomes clear: a mobility-first card that plays well for habitual riders and urban shoppers offers steady, small wins. For many, it’s not about one big signup bonus but about consistent savings that show up month after month. DiDi Finanzas fits that niche naturally—simple, immediate, and tuned to how people move. –